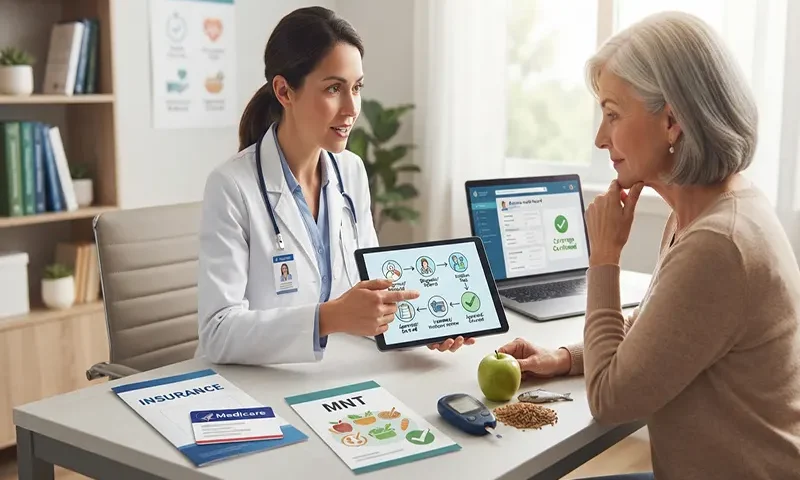
Navigating the financial side of healthcare can often feel more exhausting than managing the health condition itself. For individuals diagnosed with chronic illnesses like diabetes, kidney disease, or severe cardiovascular conditions, Medical Nutrition Therapy (MNT) administered by a Registered Dietitian Nutritionist (RDN) is not a luxury—it is essential medicine. Yet, a looming question stops many patients before they even book an appointment: Will my insurance actually pay for this?
Understanding the maze of insurance and Medicare policies regarding MNT can unlock vital financial support, transforming professional nutritional care from an out-of-pocket burden into an accessible medical benefit.
1. Medicare Coverage for MNT: What is Included?
For older adults and eligible beneficiaries, Medicare recognizes the profound value of nutritional intervention, but with specific rules, limitations, and qualifying conditions.
- Who Qualifies under Medicare Part B: Medicare coverage for MNT is not universal for all diagnoses; it is strictly targeted. Currently, Medicare Part B covers MNT services specifically for individuals diagnosed with diabetes, non-dialysis chronic kidney disease (CKD), or those who have received a kidney transplant within the last 36 months.
- The Allotted Hours: For qualifying conditions, Medicare typically covers a set number of hours during the first year of intervention—usually three hours of one-on-one nutritional counseling—followed by two hours of follow-up care in subsequent years. If your doctor determines that your condition, disease state, or treatment changes require more care, they can prescribe additional hours.
- The Mandatory Physician Referral: You cannot simply call a dietitian and bill Medicare. Medicare coverage requires a formal referral or order from a treating physician who must explicitly document that the MNT is medically necessary for your specific condition. Furthermore, the RDN providing the service must be a Medicare-enrolled provider.
2. Private Health Insurance and ACA Guidelines
Navigating commercial or employer-sponsored health insurance requires looking closely at federal mandates, individual plan types, and specific medical diagnoses.
- The Affordable Care Act (ACA) Prevention Mandate: Under the ACA, non-grandfathered private health insurance plans are required to cover certain preventative services—such as screening and counseling for obesity, gestational diabetes, and cardiovascular disease—with zero patient cost-sharing (no copay or coinsurance), provided you see an in-network provider.
- Condition-Specific Commercial Coverage: Outside of preventative screenings, private insurance coverage varies wildly depending on your specific diagnosis and insurance policy. Plans are increasingly expanding coverage for conditions like type 1 and type 2 diabetes, eating disorders, celiac disease, and severe gastrointestinal disorders. However, coverage for general wellness, weight loss without a comorbid condition, or sports nutrition is rarely covered.
- Plan Variation and Policy Riders: Because commercial plans differ from employer to employer, two people working at the same company might have entirely different nutritional benefits depending on the specific health plan tier selected. Always verify whether your policy includes an explicit “Medical Nutrition Therapy” rider or outpatient nutrition counseling benefit.
3. Navigating the System: Step-by-Step Practical Guide for Patients
Securing insurance coverage for MNT requires a proactive, methodical approach to ensure claims are processed correctly the first time.
- Secure the Medical Necessity Documentation: Start with your primary care physician or specialist. Ask them to write a clear referral that specifies your medical diagnosis (using the exact ICD-10 medical code, such as code E11 for type 2 diabetes) and explicitly recommends Medical Nutrition Therapy.
- Call Your Insurance Provider Before Your Visit: Do not guess your benefits. Call the customer service number on the back of your insurance card and ask these exact questions:
- Does my specific plan cover outpatient Medical Nutrition Therapy (MNT)?
- What are the specific CPT billing codes covered under my plan (e.g., codes 97802 and 97803)?
- Is a prior authorization required before my first session?
- Is the specific Registered Dietitian Nutritionist I want to see in-network?
- Handling Denials: If an insurance claim is initially denied, do not panic. Denials often happen due to administrative errors, such as a missing diagnostic code or a lack of prior authorization. Work with your RDN’s billing office and your physician to file an appeal with supporting medical documentation.
4. Actionable Takeaways
While insurance and Medicare structures can be intricate and restrictive, medical nutrition therapy is increasingly recognized as a vital, reimbursable component of preventative and therapeutic healthcare. With the right documentation and proactive communication, many patients successfully secure coverage for the expert guidance they need.

